Kenya Pushes for Bankable Infrastructure Projects as Africa PPP Summit Opens in Nairobi
By Samson Kurgat | NAIROBI,
Kenya has called on African governments to shift focus from discussions about the continent’s infrastructure financing gap to developing bankable projects capable of attracting private investment and accelerating economic development.
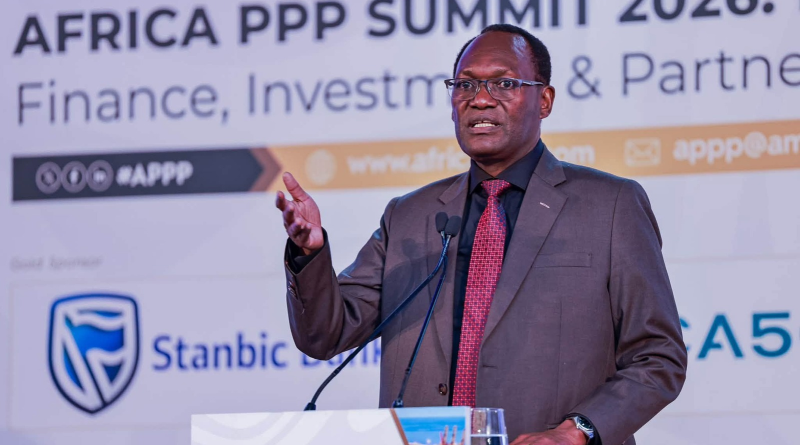
Speaking during the 16th Africa PPP Infrastructure Finance, Investment and Partnerships Summit 2026 in Nairobi, Principal Secretary for the National Treasury Dr. Chris Kiptoo said proper project preparation, effective partnerships and predictable regulatory frameworks were critical to unlocking private capital for infrastructure development. Kiptoo, who chairs the Public Private Partnerships Committee, said Kenya was strengthening its PPP framework through legal and institutional reforms while expanding its project pipeline across key economic sectors.
“An attractive project idea is not necessarily an investable project,” said Kiptoo, emphasising the need for sound feasibility studies, realistic demand projections, appropriate revenue models and proper risk allocation to make infrastructure projects attractive to investors.
Kenya currently has a pipeline of 60 PPP projects across national and county governments. Ten projects valued at approximately KSh353 billion are operational or under construction, while another 50 are at various stages of preparation and development. The Government is targeting at least KSh70 billion in additional private investment through PPPs during the current financial year. Among the flagship projects is the KSh183 billion Nairobi–Nakuru–Mau Summit Highway, alongside the Nairobi Expressway and the Kenya Defence Forces residential accommodation programme.
Kiptoo also challenged African governments to mobilise domestic institutional investments, particularly from pension funds and insurance companies, rather than relying excessively on external financing. “African capital must increasingly become a partner in financing African development,” he said, calling for investment structures that support infrastructure development while protecting investors’ interests.
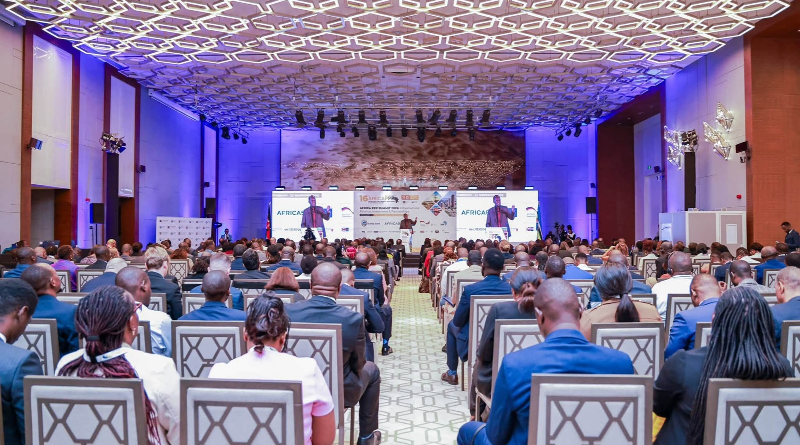
The call comes amid an estimated annual infrastructure financing requirement of between 130 and 170 billion US dollars across Africa, against a financing gap of between 68 and 108 billion dollars, despite significant domestic savings and assets across the continent.
Meanwhile, Cabinet Secretary for the National Treasury and Economic Planning John Mbadi, represented by Investments, Trade and Industry Cabinet Secretary Lee Kinyanjui, called on governments to measure infrastructure development through tangible outcomes rather than financing commitments and projects announced.
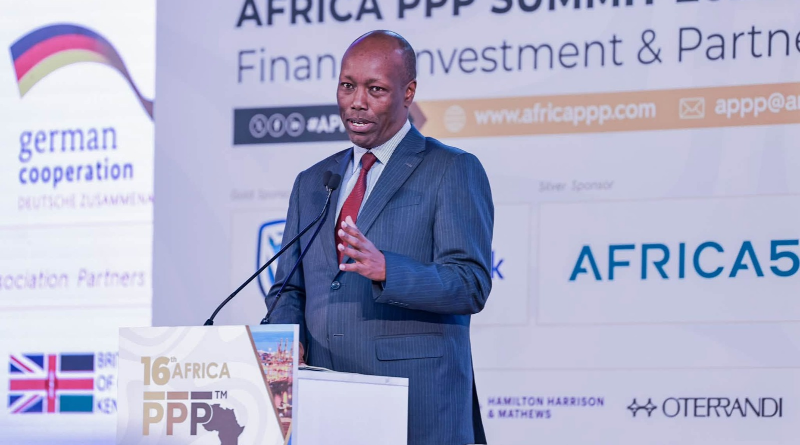
Principal Secretary for Public Investments and Asset Management Cyrell Wagunda urged governments to invest adequately in feasibility studies, environmental safeguards, land acquisition planning and appropriate risk allocation to minimise implementation delays.
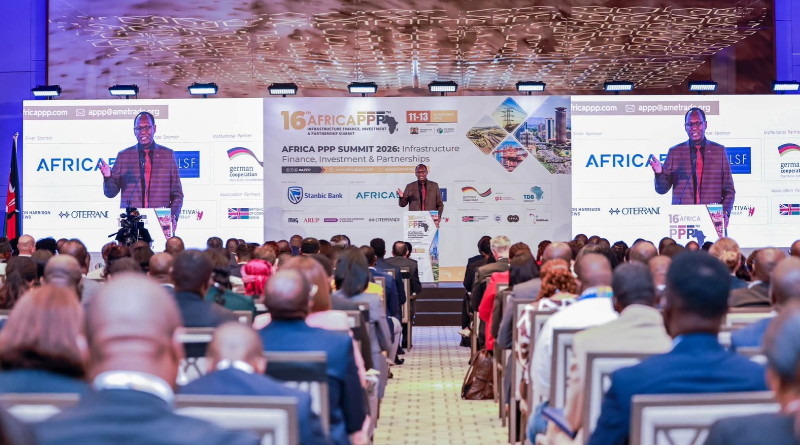
The three-day summit, running from November 11 to 13, has brought together more than 400 delegates from 36 countries, including government representatives, investors, financiers and infrastructure developers. Hosted by Kenya’s Public Private Partnerships Directorate and organised by AME Trade Limited, the summit is being held under the theme Building Africa’s Prosperity: Transformative Infrastructure, Investment and Partnerships to Accelerate Economic Development.