Beyond Sending Money: How Inclusive Payment Systems Are Impacting Rural Women in Kenya
By Carolyne Tomno
From protecting women farmers against climate shocks to enabling cross-border trade, inclusive instant payment systems are creating opportunities for financial innovation, economic participation and resilience across Africa.
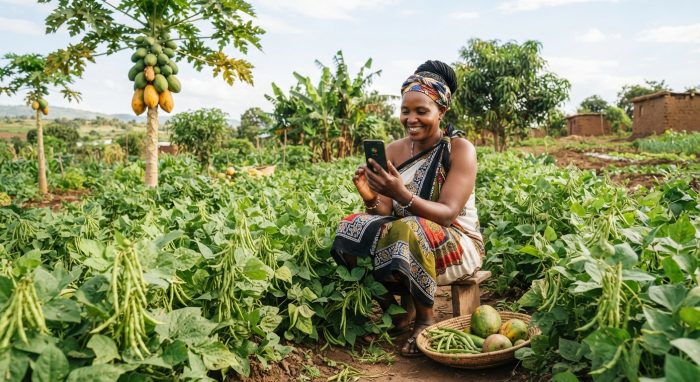
In the dry landscapes of Kathowenzi Makueni County in the South Eastern part of Kenya, a mobile phone has become more than a communication device for Milicent Mutua, and many other smallholder farmers mainly women.
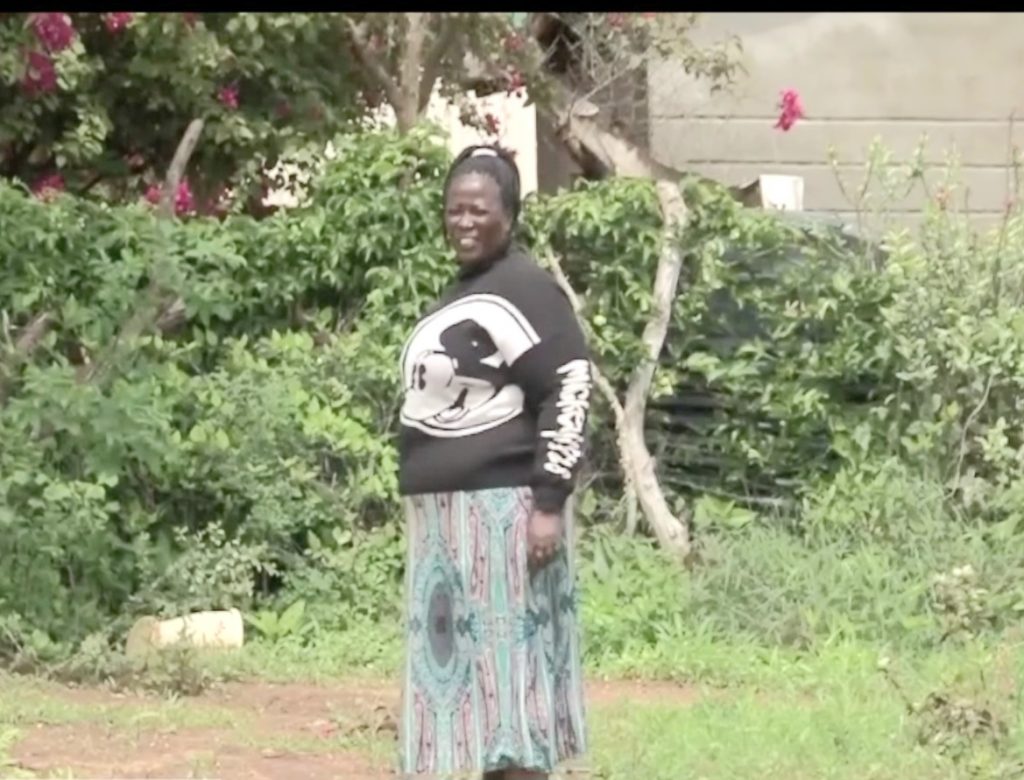
In Kenya’s rural villages like kathowenzi, it is a gateway to financial security, agricultural opportunities and a more predictable future for her family.
For years, recurrent droughts and floods threatened her livelihood, leaving her struggling with food insecurity and the cost of educating her children.
The situation was made worse by the effects of climate change. Today, access to agricultural insurance and Instant money services through her mobile phone.
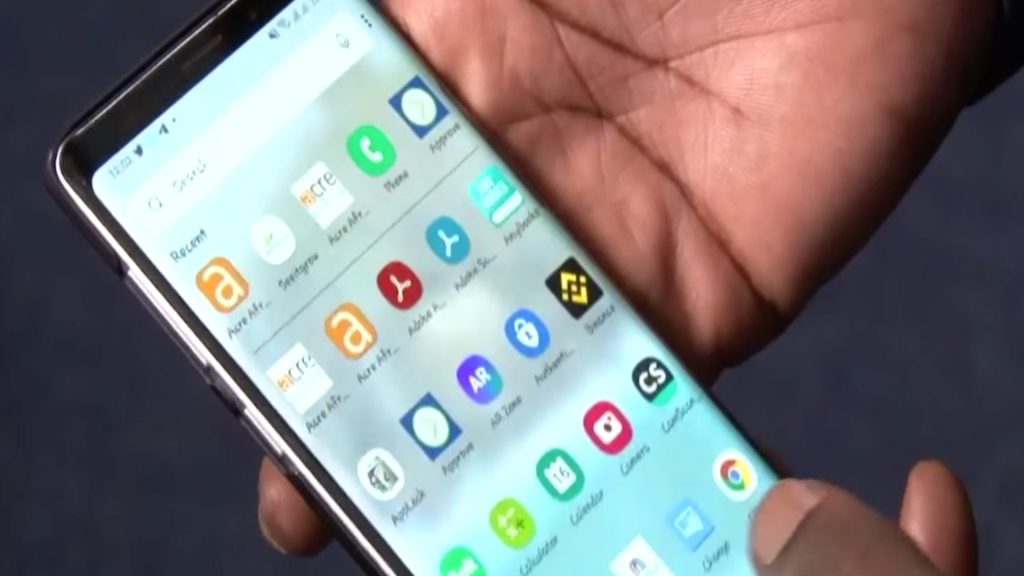
This is helping her manage some of the financial risks associated with farming. She now farms fruits vegetables and green grams and lives a comfortable life with stable income.
Through ACRE Africa’s weather-index insurance model, small holder farmers are registering for insurance using mobile-based channels, while premium payments and compensation for qualifying weather-related losses are processed electronically through mobile money platforms such as M-Pesa in Kenya.
Millicent who is now a model champion farmer in her community, , ensures other farmers mainly women who had difficulty accessing financial services due to cultural barriers, take up insurance which is paid through their mobile phones.
“Because of stable incomes, many men who had left their families to look for jobs in towns are coming back”,
Wyclife Mueke another farmer concurs with Millicent saying this had led to stabilities in families and a reduction in cases of domestic violence
Unlike conventional insurance, which often requires physical assessment of damage before compensation is approved, index-based insurance uses weather information to determine when a payout should be triggered.
Rainfall data collected through automated weather stations and satellite observations is compared against predefined thresholds.
When the agreed conditions are met, eligible farmers receive compensation through their mobile wallets without having to wait for lengthy physical claims assessments.
For Milicent, this means having a financial cushion when adverse weather threatens her agricultural income. It has also made her business transac tions easier as she can sell her farm products to customers in any part of the country.
Her dream s to see her business grow beyond borders and hopes that cross-border money systems will be harmonaized to enable seamless cross-border trade across Africa.
Her experience illustrates how digital financial infrastructure can connect previously underserved rural communities to financial services that help them withstand economic shocks.
From payment infrastructure to innovation
According to John Muthiora, Technical Payment Specialist at AfricaNenda Foundation, inclusive instant payment systems should not be viewed simply as technology projects designed to accelerate money transfers.
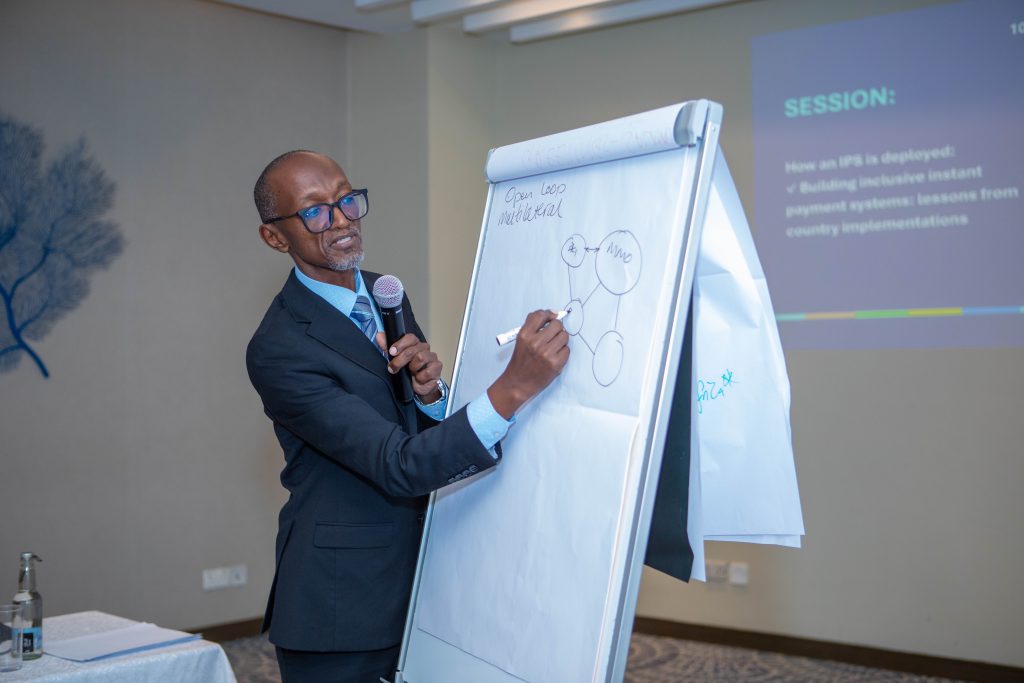
” They are national digital infrastructure that can create opportunities for innovation, competition, financial inclusion and economic growth”. Says Muthiora
The systems should be designed to make payments faster, safer and more affordable, while supporting government services, digital commerce and cross-border transactions.
Their essential characteristics include 24-hour, seven-day-a-week, 365-day availability, irrevocable credit-push transfers and accessibility through mobile channels.
More importantly, they provide a foundation upon which banks, mobile money operators, fintech companies and other licensed financial service providers can develop and deliver new products.
This creates opportunities beyond person-to-person money transfers, including merchant payments, business-to-business transactions, government disbursements, digital credit, savings and insurance services.
The potential lies in what happens when different financial service providers can connect to the same payment infrastructure rather than operating in isolated systems.
Interoperability can lower transaction costs, improve convenience and create room for fintech companies to develop solutions that respond to the needs of underserved communities.
How instant payments are strengthening women’s financial resilience
For women smallholder farmers, access to affordable and reliable financial services can determine whether they recover from a climate shock or sink deeper into poverty.
Digital payment systems can help address some of these barriers by reducing reliance on cash and connecting rural women to financial service providers.
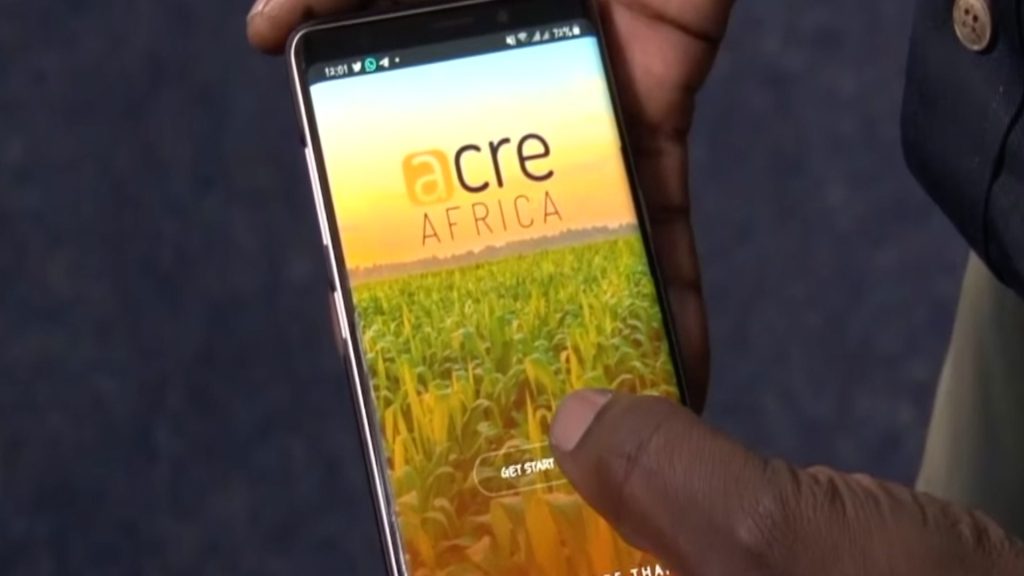
He says that through mobile-based registration, farmers can access insurance products, make premium payments and receive eligible compensation electronically
According to Cheruiyot, The impact extends beyond the individual farmer. When a household receives compensation after a weather-related loss, it has a better opportunity to purchase food, meet school expenses and reinvest in the next planting season.
The benefits can also extend to local economies. Farmers with greater financial security are better positioned to purchase inputs, transact with agricultural suppliers and participate in markets.
The gender gap: Are women benefiting equally from digital payments?
Despite the expansion of digital financial services, access to payment infrastructure does not automatically translate into equal participation.
AfricaNenda’s State of Inclusive Instant Payment Systems in Africa (SIIPS) 2025 report highlights an important gender gap.
Of the 30 instant payment systems for which transaction data was analysed, only three provided gender-disaggregated transaction information: Kenya Mobile Money, Nigeria’s NIBSS Instant Payment (NIP) and Rwanda’s eKash.
Across all three systems, men accounted for the majority of transaction volumes and values. Women also recorded lower average transaction values.
In Kenya, the report found that the average value of a transaction initiated by a woman on the Kenya Mobile Money system was US$8, compared with US$9 for men.
.
For Muthiora, the next phase of developing inclusive payment systems must therefore focus not only on building the infrastructure but also on ensuring that it responds to the needs of the people who are currently underserved.
A new frontier for African fintech innovators
The opportunity for innovation is particularly significant in agriculture, where millions of smallholder farmers need affordable ways to manage risks, access markets and transact with suppliers and buyers.
Sieka Gatabaki, of Prosper Global AgriFin , is challenging African innovators to look at how digital solutions can improve access to financial services and protect the data of women smallholder farmers engaged in cross-border trade.
” One emerging opportunity is the development of easier payment solutions that connect mobile money platforms across national borders.”
Prosper Global AgriFin has worked with financial institutions, agricultural technology companies, digital platforms and governments across Africa and Asia since 2012 to expand access to digital financial and agricultural services.
One emerging opportunity is the development of easier payment solutions that connect mobile money platforms across national borders.
Consider a Kenyan woman farmer selling agricultural produce to a buyer in Uganda or Tanzania. She may have access to mobile money locally, but receiving payments from a buyer using a different payment provider or operating in another currency can introduce additional costs, delays and complexity. Gatabaki explained
Interoperable payment systems could make such transactions easier by connecting different financial institutions and payment providers.
This will create opportunities for fintech innovators to develop cross-border payment applications, currency conversion services, digital trade platforms and financial products tailored to women traders.
Gatabaki points to the need to examine the incentives driving adoption and how payment solutions can be made more accessible across mobile money channels.
The opportunity is not limited to transferring money. Innovators can also develop solutions that help women traders establish digital transaction histories, improve data security and build financial identities that could eventually support access to credit and insurance.
The case for cross-border interoperability
And for Millicent and other small holder farmers across Africa there is hope as there is need for interconnected payment systems is becoming increasingly important as African countries deepen regional trade and economic integration.
AfricaNenda’s SIIPS 2025 report shows that the continent processed more than 64 billion instant payment transactions in 2024, valued at nearly US$2 trillion.
It identified 36 live instant payment systems across 31 African countries.
The report also found that 16 domestic systems were classified as cross-domain, allowing transactions between different types of financial institutions, including banks and non-bank providers.
However, cross-border interoperability remains a significant opportunity. Only 11 of the 36 systems enabled cross-border payments, including three regional systems.
.For women traders, this could mean receiving payments from customers in neighbouring countries more easily, reducing dependence on cash and improving the security of business transactions.
Building an inclusive digital economy
While the growth of instant payment systems presents significant opportunities, the infrastructure must be designed around the needs of its intended users.
For women traders, the promise is easier access to markets and payments beyond national borders.And for African innovators, the emerging payment ecosystem presents an opportunity to develop technologies that make financial services more accessible, competitive and responsive to the realities of the continent.
The ultimate measure of success will not simply be how quickly money moves across payment networks, but how effectively that infrastructure enables women, farmers and small businesses to participate in and benefit from Africa’s growing digital economy.
Despite the expansion of instant payment systems, benefits remain unevenly distributed particularly along gender lines.
Women across Africa still face unique and intersecting barriers such as limited phone ownership, lower digital literacy, constrained mobility, and restrictive socio-economic norms.